Tax Planning Services for Smarter Business Savings
Latest Update: November 2026
Tax planning continues to be an important part of business financial management. This article examines how companies can manage tax exposure, identify legitimate savings opportunities, and make better financial decisions through year-round planning.
Answer Snippet
A tax planning service for business helps companies identify legitimate tax-saving opportunities, manage tax liabilities, and make informed financial decisions throughout the year. By reviewing financial performance, business structures, expenses, and applicable deductions, tax professionals help businesses prepare for upcoming obligations while supporting long-term financial stability.
Key Facts at a Glance
- Tax planning works best when integrated into regular financial reviews rather than limited to year-end activities.
- Accurate bookkeeping helps identify eligible deductions, credits, and potential reporting inconsistencies.
- Business structure influences how income is reported and how tax liabilities are calculated.
- Estimated tax payments require regular attention as business income and profitability change.
- Equipment purchases and capital investments can have significant tax implications.
- Supporting documentation is essential for substantiating deductions and maintaining compliance.
Quick Read
- Tax planning focuses on future tax obligations and financial decisions.
- Regular reviews help identify potential savings before important deadlines.
- Business structure, expenses, payroll, and investments influence tax outcomes.
- Poor documentation and delayed financial reporting can lead to missed opportunities.
- Professional guidance helps align tax decisions with business objectives.
Introduction
A profitable business can still incur unnecessary tax expenses when financial decisions are made without considering their tax implications. Purchasing equipment, hiring employees, changing business structures, or expanding into another state can affect taxable income and future obligations.
The challenge is that many businesses review these decisions only when preparing their annual returns. By then, certain opportunities may have passed, leaving limited scope to change the outcome.
A structured approach to business tax planning services allows companies to evaluate their financial position throughout the year. It connects accounting information with upcoming business decisions, helping owners understand potential tax consequences before committing resources.
Understanding Business Tax Planning
Tax planning involves reviewing a company's financial activities and identifying legally available ways to manage its tax liability. The process considers income, deductible expenses, tax credits, business structure, investments, and applicable federal and state requirements.
Unlike a filing-focused approach, planning looks ahead. For example, a company considering an equipment purchase may need to evaluate its timing, cash flow implications, and available depreciation treatment.
Similarly, a business experiencing rapid revenue growth may need to revisit estimated tax payments to avoid an unexpected balance when filing its return.
Effective small business tax planning connects these considerations with financial records and operating plans.
Tax Planning and Tax Preparation Compared
Tax planning and tax preparation are closely related, but they serve different purposes. Planning focuses on future opportunities, while preparation reports financial activities that have already taken place.
|
Tax Planning |
Tax Preparation |
|
Evaluates future tax obligations and opportunities. |
Reports completed financial transactions. |
|
Identifies potential deductions and credits. |
Calculates eligible deductions and credits using available records. |
|
Evaluates business structure and investment decisions. |
Reports income and expenses under applicable tax rules. |
|
Supports estimated tax payments and financial planning. |
Prepares and files required tax returns. |
|
Takes place throughout the year. |
Generally follows the applicable filing schedule. |
Both activities are important. Accurate preparation establishes the reporting foundation, while proactive planning helps businesses make better financial decisions.
Business Benefits of Proactive Tax Planning
A structured tax strategy offers benefits beyond reducing the final tax bill.
- Better cash flow management: Understanding expected tax obligations helps businesses allocate funds, plan payments, and avoid liquidity pressure around filing deadlines.
- Improved financial decisions: Management can evaluate the tax implications of hiring, purchasing assets, expanding operations, or changing ownership arrangements before committing funds.
- Fewer compliance surprises: Periodic reviews can identify reporting gaps, inconsistent records, and potential tax exposure before they become more difficult to address.
- Greater financial visibility: Tax projections help business owners understand how changes in revenue, expenses, and profitability may affect their financial position.
For growing companies, working with a business tax advisor also provides professional guidance when financial decisions involve more complicated tax considerations.
Ways Tax Planning Can Reduce Business Expenses
Tax savings generally come from making informed decisions and claiming eligible deductions and credits supported by proper documentation.
For instance, a company planning to purchase machinery may need to compare available depreciation options and understand how the purchase affects taxable income. The timing of placing an asset into service can also matter. Other opportunities may involve reviewing employee benefit arrangements, qualifying business expenses, retirement plan contributions, and available tax credits.
However, not every expense qualifies for a deduction. A professional review helps distinguish legitimate opportunities from assumptions that could create compliance problems. The value of tax planning for small business owners lies in identifying these opportunities early enough to take appropriate action.
Common Tax Planning Errors
Even financially established businesses can make avoidable tax-planning mistakes.
- One common problem is treating tax planning as an annual exercise. Delayed reviews leave little time to adjust estimated payments, evaluate investments, or address reporting inconsistencies.
- Another mistake is relying on incomplete financial information. Unreconciled bank accounts, missing expense documentation, and inaccurate payroll records can affect tax projections.
- Businesses also sometimes overlook changes in their operating structure. Adding a new entity, entering another state, or changing ownership arrangements can introduce additional reporting considerations.
- Finally, assuming every business expense is deductible can lead to incorrect claims. Expenses should be evaluated under applicable tax rules and supported by appropriate records.
The Stratax Tax Planning Process
A practical planning process should connect financial information with the decisions management needs to make.
Initial financial review: The process begins with an examination of financial statements, previous tax returns, accounting records, and the company's current operating structure.
Tax exposure assessment: Income, expenses, deductions, credits, and existing tax obligations are reviewed to identify potential risks and planning opportunities.
Tax projection: Available financial information is used to estimate the company's tax position and evaluate possible changes in business performance.
Strategy development: Recommendations are developed around relevant business decisions, including investments, compensation, entity structure, and estimated payments.
Implementation and monitoring: Agreed actions are tracked, and the plan is reviewed as financial circumstances and applicable regulations change.
This approach makes tax planning a continuing management activity rather than a last-minute exercise.
Essential Documents for Business Tax Planning
The quality of tax planning depends considerably on the information available. Businesses should maintain organized records and provide supporting documents relevant to their financial activities.
|
Document |
Purpose |
|
Previous tax returns |
Establishes historical tax positions and identifies recurring issues. |
|
Profit and loss statements |
Shows revenue, expenses, and operating profitability. |
|
Balance sheets |
Provides information about assets, liabilities, and equity. |
|
Bank and credit card statements |
Supports transaction reviews and expense reconciliation. |
|
Payroll records |
Helps evaluate compensation, employment taxes, and employee benefits. |
|
Asset purchase records |
Supports depreciation calculations and capital expenditure reviews. |
|
Loan and interest statements |
Helps assess financing costs and applicable deductions. |
|
Sales and expense invoices |
Provides supporting evidence for recorded transactions. |
Proper documentation makes it easier to substantiate reported figures, investigate discrepancies, and prepare accurate tax returns.
Available Business Tax Planning Services
Businesses can access tax planning through different professional and technology-based arrangements. The appropriate option depends on operational complexity and the level of guidance required.
- Technology-Enabled Financial Tools and Advisory: Financial software can organize transactions, generate reports, and provide visibility into income and expenses. Some platforms also offer advisory support. However, software-generated insights should not replace professional interpretation of complex tax matters.
- Specialized Tax and Wealth Guidance: These professionals may coordinate business tax considerations with ownership, investment, retirement, and succession objectives. This approach can be useful when business and personal financial decisions overlap.
- CPA Firms Offering Integrated Advisory Support: CPA firms provide tax planning alongside accounting and financial advisory services. Their support may include tax projections, entity structure reviews, deduction analysis, compliance assessments, and year-round financial guidance.
- Tax Professionals Serving Smaller Businesses: Independent tax professionals and smaller specialist practices can provide focused guidance to businesses with relatively straightforward requirements. Their suitability depends on their qualifications, experience, and familiarity with the company's industry and tax circumstances.
Understanding Business Tax Planning Costs
The cost of tax planning depends on the scope of work, business structure, number of entities, financial complexity, and level of ongoing support.
- One-Time Tax Consultations: A consultation generally involves a defined review of a particular tax question or business decision. Fees depend on the professional's experience and the time required.
- Written Tax Plans for Smaller Businesses: A written plan requires a more detailed examination of financial records, tax exposure, and potential savings opportunities. Its cost depends on the depth of analysis and recommendations required.
- Planning for Complex or Multiple Business Entities: These engagements involve additional analysis, particularly when operations span several states or include multiple ownership arrangements.
- Recurring Accounting and Tax Advisory: Monthly arrangements may include periodic financial reviews, tax projections, and implementation support. CPA firms use different pricing models, including hourly billing, fixed fees, and value-based engagements.
Businesses should request a clear engagement scope and fee estimate before proceeding. The objective is to understand what the engagement covers, how frequently reviews take place, and what deliverables are included.
Looking for Reliable Tax Preparation Assistance? We're Here to Help!
Get Accurate Tax Preparation Without the Stress!
How Stratax Advisors Helps
Stratax Advisors approaches tax planning as an integral part of business financial management. The focus is on understanding the company's financial position, identifying relevant tax considerations, and helping management make informed decisions.
Support can include reviewing financial records, evaluating potential deductions and credits, assessing business structure considerations, and developing tax projections. Regular financial reviews also help identify inconsistencies that could affect reporting accuracy or future tax obligations.
By connecting accounting information with tax considerations, Stratax Advisors helps businesses improve financial visibility, prepare for upcoming obligations, and approach important decisions with greater confidence.
Conclusion: Building a More Proactive Tax Strategy
Tax savings are not simply a matter of identifying deductions when a return is due. They depend on the quality of financial information, the timing of business decisions, and a clear understanding of applicable tax rules.
A consistent planning process gives management greater control over tax exposure and helps align financial decisions with business priorities. For companies looking to improve financial discipline, proactive tax planning is an important part of responsible business management.
Frequently asked questions
Professional tax planning typically involves reviewing financial records, evaluating the company's tax position, identifying eligible deductions and credits, and estimating future obligations. Depending on the engagement, it may also include reviewing business structure, investments, compensation arrangements, and estimated payments. The objective is to develop practical recommendations that support tax efficiency while maintaining compliance with applicable regulations.
Professional guidance can be valuable when business decisions have significant tax implications. A qualified advisor can help evaluate investments, ownership changes, compensation arrangements, and other financial decisions. Businesses with multiple entities, operations across states, or changing profitability may particularly benefit from periodic professional reviews. Always verify the advisor's qualifications and experience before engaging their services.
Growing businesses, companies with fluctuating income, multi-entity organizations, and businesses making significant capital investments can benefit from structured tax planning. However, smaller businesses can also gain value from reviewing deductions, estimated payments, and financial records. The appropriate level of planning depends on the company's financial complexity, operating structure, and future objectives.
Start by considering your business structure, annual revenue, profitability, investment activity, and reporting requirements. A company with straightforward operations may need periodic consultations and an annual tax review. Businesses with multiple entities, interstate activities, or major financial transactions may require more frequent projections and detailed advisory support.
Tax planning focuses on identifying opportunities to manage future tax liabilities through informed financial decisions, while tax preparation involves calculating, reporting, and filing taxes based on completed financial transactions. Planning takes place throughout the year and may include reviewing deductions, investments, business structure, and estimated payments. Tax preparation ensures that the business meets its filing obligations accurately and on time. Both are essential for effective tax management.
Fees depend on the complexity of your business and the scope of professional support. A consultation, a detailed written tax plan, and an ongoing advisory arrangement involve different levels of work. Request a written estimate outlining the services, review frequency, and deliverables. This makes it easier to compare proposals and understand the value of the engagement.
What’s Next? Take the Next Step with Stratax Advisors
Tax planning should reflect your business's actual financial position, not assumptions based on previous years. Stratax Advisors helps businesses review their financial information, assess tax considerations, and develop practical strategies that support better financial decisions. If your current approach is largely focused on annual tax filing, consider a more structured planning process. Connect with Stratax Advisors to discuss your business's requirements and explore how proactive tax planning can support smarter financial management.
About the Author
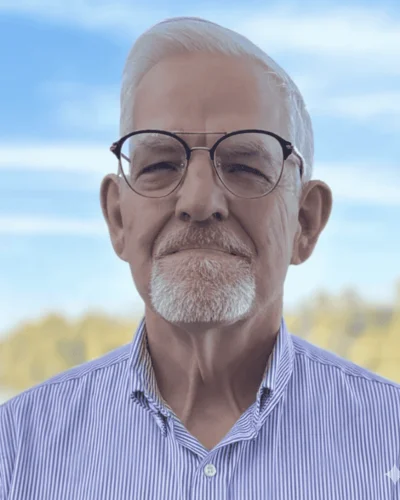
Daniel (“Dan”) T. Jones, CPA brings over 40 years of experience in finance, management, and advisory services to Stratax Advisors. He works closely with privately owned growth companies, business owners, and high-net-worth individuals, providing business, tax, and financial planning support across industries including real estate, manufacturing, retail, and professional services. A former KPMG partner, Dan has also founded and led multiple successful entrepreneurial ventures in real estate and financial services. He holds a B.S. with honors in Business Administration and Accounting from the University of North Carolina at Chapel Hill and is actively involved in community leadership.
Let’s Take Our Conversation Ahead
At Stratax, we empower individuals and businesses to make confident financial decisions. With deep expertise and unwavering precision, we deliver solutions that safeguard your future and accelerate your success.
Schedule a Meeting