1099 vs. W-2: What’s the Difference for Businesses?
Answer Snippet
The difference between a 1099 and a W-2 depends on whether a worker is an independent contractor or an employee. US businesses generally issue Form W-2 to employees to report wages and tax withholding, while Form 1099-NEC reports qualifying nonemployee compensation. Worker classification depends on the actual working relationship, not simply the contract or payment method.
Quick Read
- Form W-2: Reports employee wages and applicable tax withholding.
- Form 1099-NEC: Reports qualifying nonemployee compensation.
- Worker classification: Depends on the actual working relationship and applicable legal tests.
- Payroll taxes: Employers generally handle applicable payroll withholding and employer-side employment taxes for employees.
- Compliance risks: Misclassification can result in unpaid taxes, interest, penalties, and potential employment law claims.
Introduction
Hiring employees and engaging independent contractors are two common ways US businesses meet their workforce needs. However, each arrangement involves different tax reporting responsibilities, employment obligations, and financial considerations.
Understanding 1099 vs W2 is essential for businesses that want to manage labor costs, maintain accurate accounting records, and comply with federal tax requirements. Although independent contractors may offer flexibility for specific projects, businesses cannot simply choose contractor status to avoid payroll taxes or employee obligations.
The correct classification depends on the actual working relationship and the applicable federal and state rules. Understanding these differences helps business owners make informed staffing decisions and avoid preventable compliance problems.
1099 vs W2: Key Differences for Businesses
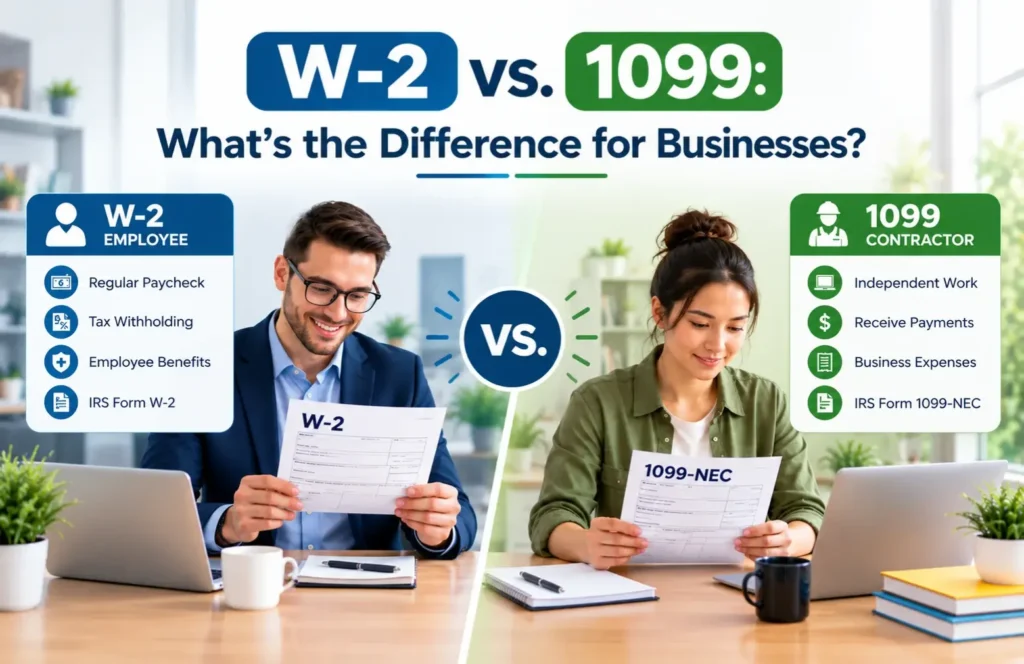
Form W-2 is generally used for employees, while Form 1099-NEC is used to report qualifying nonemployee compensation paid to independent contractors.
|
Comparison |
W-2 Employee |
1099 Contractor |
|
Working relationship |
Employer-employee relationship |
Independent business relationship |
|
Work direction |
Employer generally has the right to control how work is performed |
Generally has greater independence over work methods |
|
Tax withholding |
Employer withholds applicable payroll taxes |
Contractor generally handles their own taxes |
|
Employment taxes |
Employer pays applicable employer-side taxes |
Business generally does not pay employer payroll taxes on properly classified contractor compensation |
|
Benefits |
May qualify for employee benefits |
Generally manages their own benefits |
|
Payment |
Salary, wages, or commissions |
Project fees or agreed service payments |
|
Tax reporting |
Form W-2 |
Form 1099-NEC when reporting requirements apply |
These distinctions are general guidelines. The actual classification depends on the facts, and special federal or state rules may apply.
How to Determine Whether a Worker Is an Employee or Independent Contractor
The IRS considers the degree of control and independence in the working relationship. Three categories are particularly relevant.
1. Behavioral Control
Behavioral control concerns whether a business has the right to direct how a worker performs the job. Detailed instructions, required training, and close supervision may indicate an employment relationship.
An independent contractor generally has greater discretion over the methods used to complete an assignment, although the business can still establish project requirements and deadlines.
2. Financial Control
Financial control examines how the business aspects of the relationship are managed. Relevant factors include the worker's investment in equipment, unreimbursed expenses, opportunity for profit or loss, and ability to offer services to other clients.
A worker operating an independent business may demonstrate contractor characteristics, but no single factor determines the classification.
3. Nature of the Relationship
Written agreements, employee benefits, the expected duration of the relationship, and the nature of the services can also matter.
A contractor agreement does not automatically establish independent contractor status. Businesses must evaluate the actual arrangement rather than relying solely on contractual wording. If federal tax classification remains unclear, they can consider requesting an IRS determination through Form SS-8.
W-2 vs 1099 Tax Differences
The W-2 vs 1099 tax differences affect payroll administration, business expenses, and financial planning.
Payroll Taxes and Withholding
Employers generally withhold applicable federal income tax and the employee's share of Social Security and Medicare taxes. They also generally pay the employer's share of these taxes and may have federal and state unemployment tax obligations.
Properly classified independent contractors generally receive payments without regular employee payroll tax withholding. They are typically responsible for reporting their income and paying applicable income and self-employment taxes.
Benefits and Employment Costs
Employees may receive health insurance, retirement benefits, paid leave, and other compensation depending on the employer's plans and applicable requirements. Contractors generally manage their own benefits and operating expenses.
Businesses should compare total costs rather than just wages and contractor fees. Payroll taxes, benefits, equipment, administration, and the duration of the engagement can all affect the final cost.
Accounting and Recordkeeping
Businesses should maintain accurate payroll records, contractor invoices, payment documentation, and supporting tax forms. Regular reconciliation helps finance teams verify labor expenses, prepare financial statements, and support tax reporting.
1099-NEC Filing Requirements for US Businesses
Understanding the 1099-NEC filing requirements helps businesses manage information reporting and avoid missed deadlines.
Businesses commonly collect Form W-9 from independent contractors to obtain their taxpayer identification information. They should maintain accurate payment records and determine whether each payment meets the applicable reporting requirements.
For qualifying nonemployee compensation paid in 2026, the general federal Form 1099-NEC reporting threshold is $2,000, subject to exceptions and special rules. The threshold for payments made before 2026 was generally $600.
The general deadline for furnishing Form 1099-NEC to recipients and filing it with the IRS is January 31 following the payment year. When that date falls on a weekend or applicable legal holiday, the deadline generally moves to the next business day. For 2026 payments, the general deadline is February 1, 2027.
Businesses should verify the current IRS instructions and applicable state reporting requirements before filing.
Why Employee Misclassification Can Be Costly
Incorrectly classifying an employee as an independent contractor can create significant financial and legal risks.
Potential consequences include unpaid employment taxes, interest, penalties, and corrected tax filings. Depending on the circumstances, businesses may also face claims involving minimum wages, overtime, workers' compensation, unemployment insurance, or employee benefits.
To reduce these risks, businesses should review worker classifications when engagements begin and whenever working arrangements change. Maintaining appropriate documentation and seeking qualified tax or legal advice when necessary can help prevent avoidable compliance problems.
Finance Impact: Budgeting for Employees and Contractors
The 1099 vs W2 decision affects more than tax forms. It also influences labor budgeting, expense classification, cash flow, and financial reporting.
Employee costs may include wages, employer payroll taxes, benefits, and payroll administration. Contractor expenses may include project fees, service invoices, and other agreed payments.
Finance teams should record these expenses consistently and reconcile payroll reports, contractor invoices, and general ledger balances. Reliable records help management compare labor costs, forecast cash requirements, identify discrepancies, and prepare for year-end reporting.
Businesses should base staffing decisions on operational needs and applicable classification rules rather than cost savings alone.
How Stratax Advisors Supports Better Accounting Practices
Accurate financial records help US businesses monitor operating expenses, maintain reliable reports, and prepare for tax season. Consistent accounting procedures are particularly important when managing employee compensation, contractor payments, and supporting documentation.
Stratax Advisors recognizes the importance of organized financial records and dependable accounting processes. Businesses can benefit from consistent expense tracking, regular reconciliations, and clear documentation of payroll and contractor-related transactions.
These practices help management understand labor costs, identify discrepancies, and make better-informed financial decisions.
Worker classification and tax compliance should be evaluated under the applicable US rules, with qualified tax or legal advice sought when necessary. Maintaining accurate accounting records supports this process by keeping financial information organized and accessible.
Conclusion
Understanding 1099 vs W2 is essential for US businesses that hire employees, freelancers, consultants, and other service providers. Form W-2 generally applies to employees, while Form 1099-NEC reports qualifying nonemployee compensation.
The correct classification depends on the actual working relationship and applicable legal requirements. Businesses must also consider payroll taxes, reporting deadlines, labor costs, and potential misclassification risks.
By establishing sound classification procedures and maintaining accurate financial records, businesses can manage workforce expenses more effectively and reduce avoidable reporting problems.
Frequently asked questions
Issue Form W-2 when a worker qualifies as an employee under applicable rules. Use Form 1099-NEC for qualifying payments to independent contractors when reporting requirements apply. Classification depends on the actual working relationship, not simply the contract or payment method.
Employers generally withhold applicable payroll taxes and pay employer-side employment taxes for W-2 employees. Independent contractors generally handle their own income and self-employment taxes. Businesses should also compare benefits, administration, and other labor costs.
For qualifying nonemployee compensation paid in 2026, the general federal reporting threshold is $2,000, subject to exceptions. The general deadline for furnishing Form 1099-NEC and filing it with the IRS is January 31 following the payment year, adjusted for weekends and applicable holidays. For 2026 payments, the general deadline is February 1, 2027.
Contractors may reduce certain employer payroll and benefit costs, but their fees can be higher. Businesses should compare total costs, including wages, payroll taxes, benefits, administration, and contractor fees. Cost savings alone cannot justify misclassifying an employee.
Misclassification can result in unpaid employment taxes, interest, penalties, and corrected tax filings. Businesses may also face state-level claims involving wages, overtime, benefits, or workers' compensation. Reviewing classifications regularly and seeking qualified tax or legal advice can help reduce these risks.
What’s Next?
Accurate financial records support better business decisions and more reliable reporting. Stratax Advisors encourages businesses to review their accounting processes and maintain consistent financial documentation. Contact Stratax Advisors to discuss your business's accounting needs.
About the Author
Daniel (“Dan”) T. Jones, CPA brings over 40 years of experience in finance, management, and advisory services to Stratax Advisors. He works closely with privately owned growth companies, business owners, and high-net-worth individuals, providing business, tax, and financial planning support across industries including real estate, manufacturing, retail, and professional services. A former KPMG partner, Dan has also founded and led multiple successful entrepreneurial ventures in real estate and financial services. He holds a B.S. with honors in Business Administration and Accounting from the University of North Carolina at Chapel Hill and is actively involved in community leadership.
Let’s Take Our Conversation Ahead
At Stratax, we empower individuals and businesses to make confident financial decisions. With deep expertise and unwavering precision, we deliver solutions that safeguard your future and accelerate your success.
Schedule a Meeting